The US Economy, Week of Nov 2-6, 2026: Where the Cycle Stands
I track the US economy each week through the indicators that the Federal Reserve publishes: inflation, interest rates and the yield curve, jobs and layoffs, credit spreads, mortgage rates, consumer sentiment and GDP. Each chart covers the last three years of data from FRED, one metric per chart.
Glossary: what the terms mean
- Inflation (CPI): How much more things cost than a year ago. The Consumer Price Index measures inflation with a basket of groceries, gas, rent and everyday goods.
- Core inflation: The same measure with food and fuel removed. Food and fuel prices change a lot from month to month, so core shows the slower, stickier trend.
- 3-month annualized pace: Inflation over just the last three months, converted to a yearly rate. The 3-month pace changes direction before the year-over-year number does, so the 3-month pace gives an early warning.
- Fed rate (fed funds): The short-term interest rate the Federal Reserve sets. Lenders set mortgage, car loan and credit card rates from the Fed rate. A higher Fed rate slows the economy. A lower Fed rate stimulates the economy.
- Treasury yield (2-year, 10-year): The interest rate the US government pays to borrow for 2 or 10 years. The 2-year tracks where markets expect the Fed rate to go. The 10-year reflects longer-run growth and inflation.
- Basis point (bp): One hundredth of a percentage point. 50bp = 0.50%.
- Yield curve: The 10-year rate minus the 2-year rate. The yield curve is normally positive, because a longer loan pays more.
- Inverted curve: A yield curve below zero. Investors accept less to lend for 10 years than for 2, which they only do when they expect a slowdown. An inverted curve came before every US recession in the last 50 years, usually about a year early, and an inverted curve also gave false alarms.
- Unemployment rate: The share of people who want a job, search for one, and don't have one.
- Payrolls (jobs added): The net number of jobs employers added in a month.
- Participation rate: The share of working-age adults who have a job or actively search for one. If people quit the job search, the unemployment rate can fall even though nobody found a job. The participation rate shows when people quit the job search.
- Sahm rule: A recession alarm that FRED publishes as the Sahm Rule Recession Indicator. When the 3-month average unemployment rate rises half a point above its low of the past year, the US economy is almost always already in a recession.
- Jobless claims: The number of people who file for unemployment benefits for the first time each week. Jobless claims are the fastest weekly data on layoffs.
- High-yield credit spread: The extra interest risky companies pay to borrow compared with the government. The posts use the ICE BofA US High Yield spread. A low spread means lenders see little risk. A sharp rise in the spread means lenders see more risk.
- 30-year mortgage rate: The interest rate on a typical home loan.
- Consumer sentiment: A monthly University of Michigan survey of how people feel about their finances and the economy.
- GDP growth: How fast the total output of the economy grows, after inflation, at a yearly pace. The Bureau of Economic Analysis reports GDP growth every quarter and revises the number later.
- WTI oil: The benchmark price of a barrel of US crude oil. The WTI price moves gas prices and CPI inflation quickly.
- Recession: A broad, sustained decline in economic activity: lower output, higher unemployment, weaker spending.
- Soft landing: The Fed lowers inflation, and no recession follows.
- Base, bear and bull case: The most likely path, the worse path, and the better path over the next year, each with a rough probability.
This week's read
A large language model (LLM) generates the analysis below from the Federal Reserve data in the charts. The analysis is not financial advice.
The call this week is MID/LATE-CYCLE, with caution. The October jobs report was better: +165k payrolls, unemployment down to 4.1%, and an upward revision to September. Oil fell under $100. Spreads widened and the curve flattened a little. The late-cycle call holds and the bear case eases.
Inflation
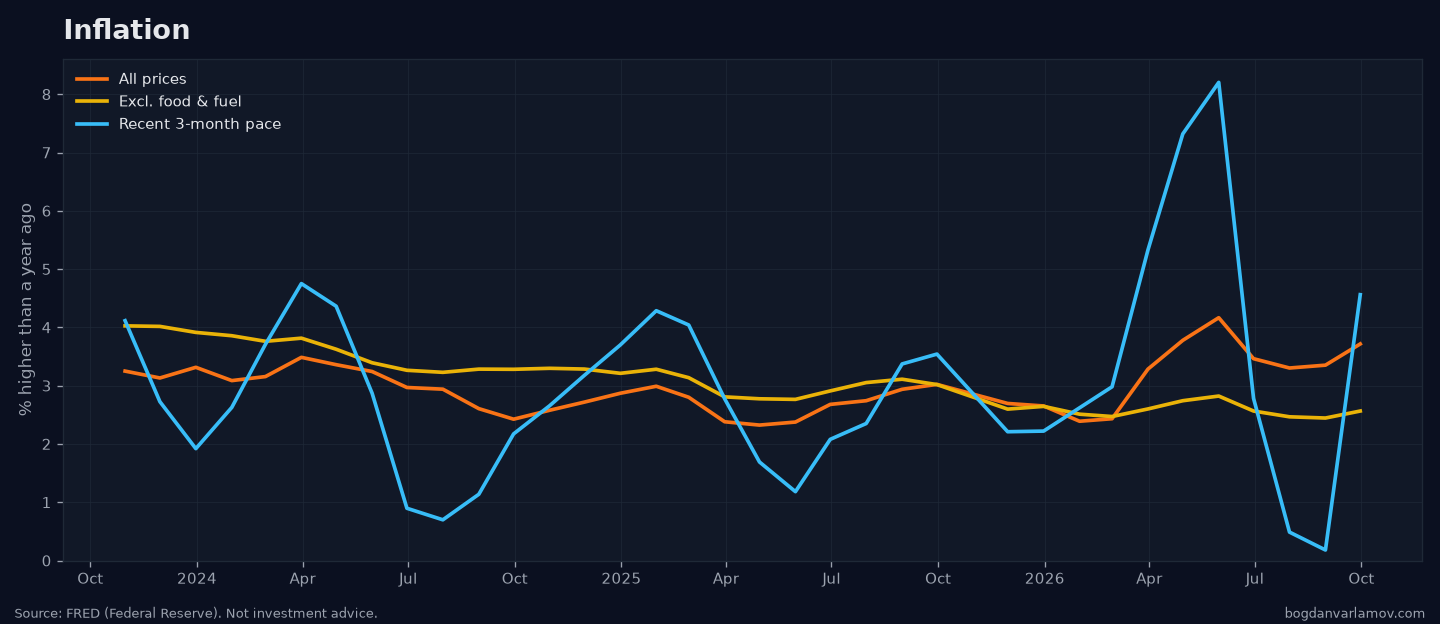
Headline and core inflation, and the recent 3-month pace.
Oil, the input that moves headline inflation fastest.
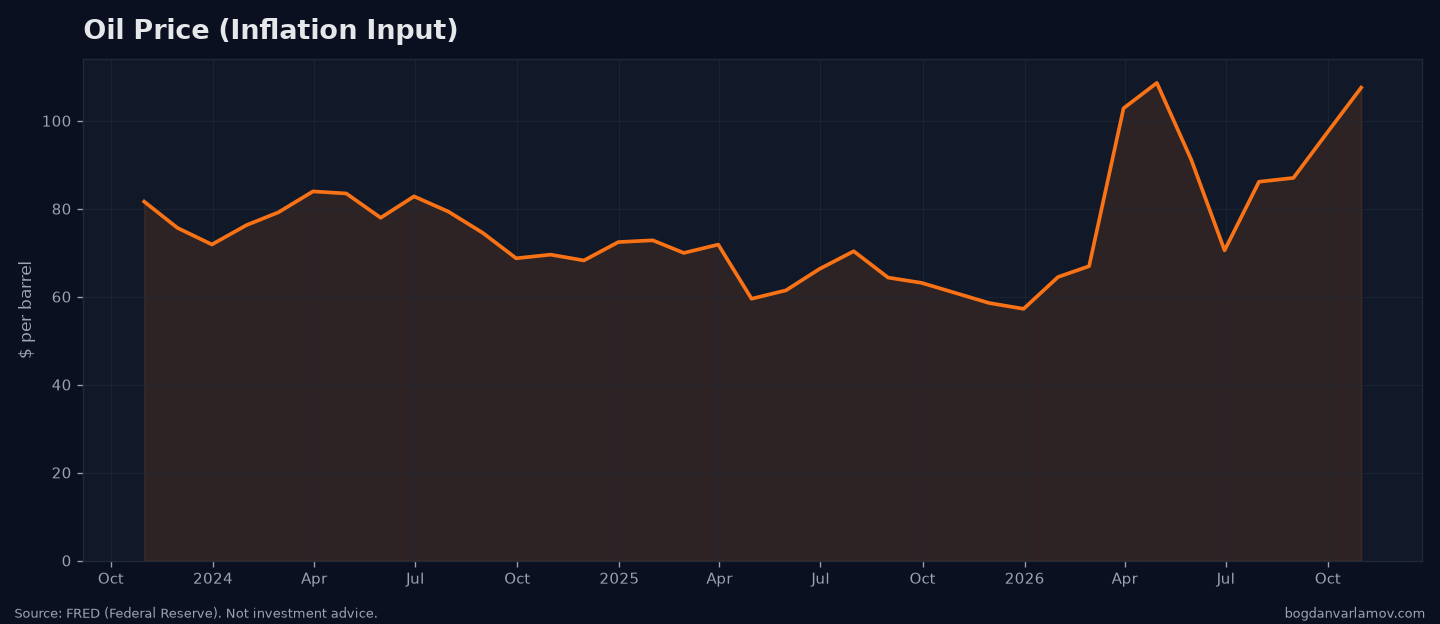
There is no new inflation data this week, so the September figures still stand: headline CPI 3.7%, a 3-month annualized rate of 4.6%, and core CPI 2.6%. Oil is still the driver. WTI crude fell from about $103 last week to $99.64 (Nov 3). October still averaged about $108, well above September's ~$97, so the October CPI reading is unlikely to cool.
Rates and the Fed
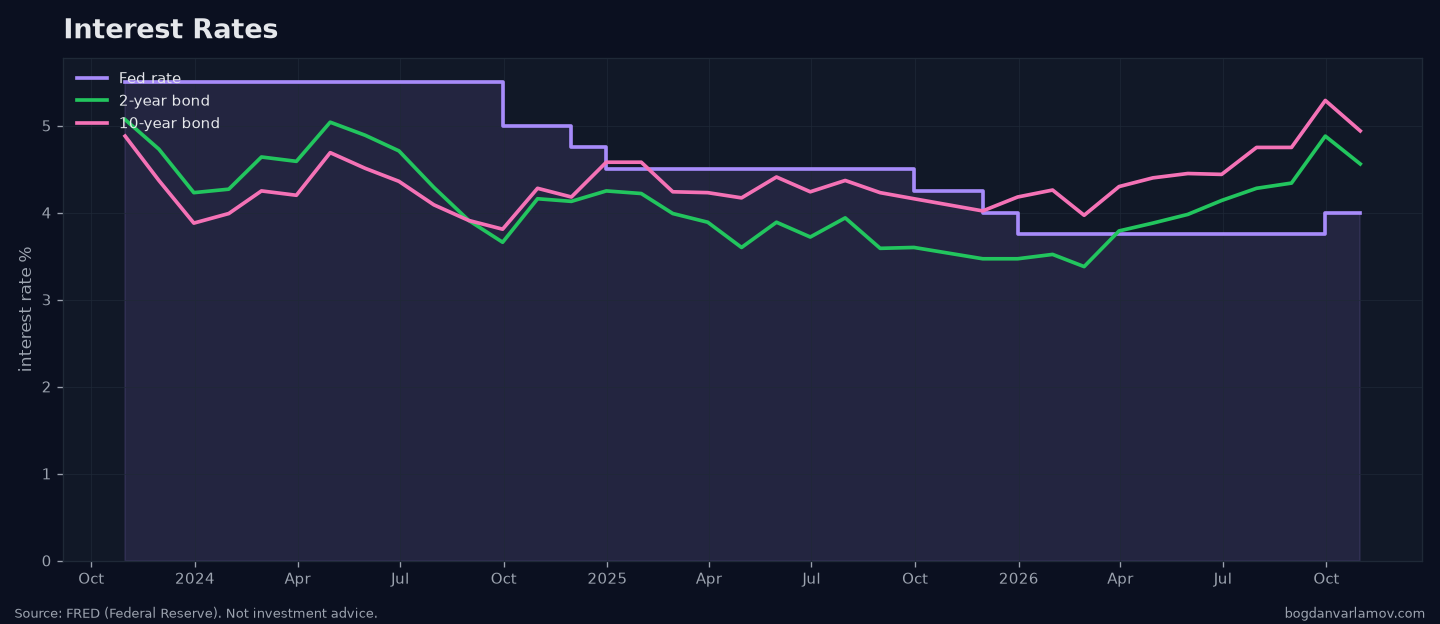
The Fed rate against the 2- and 10-year bond.
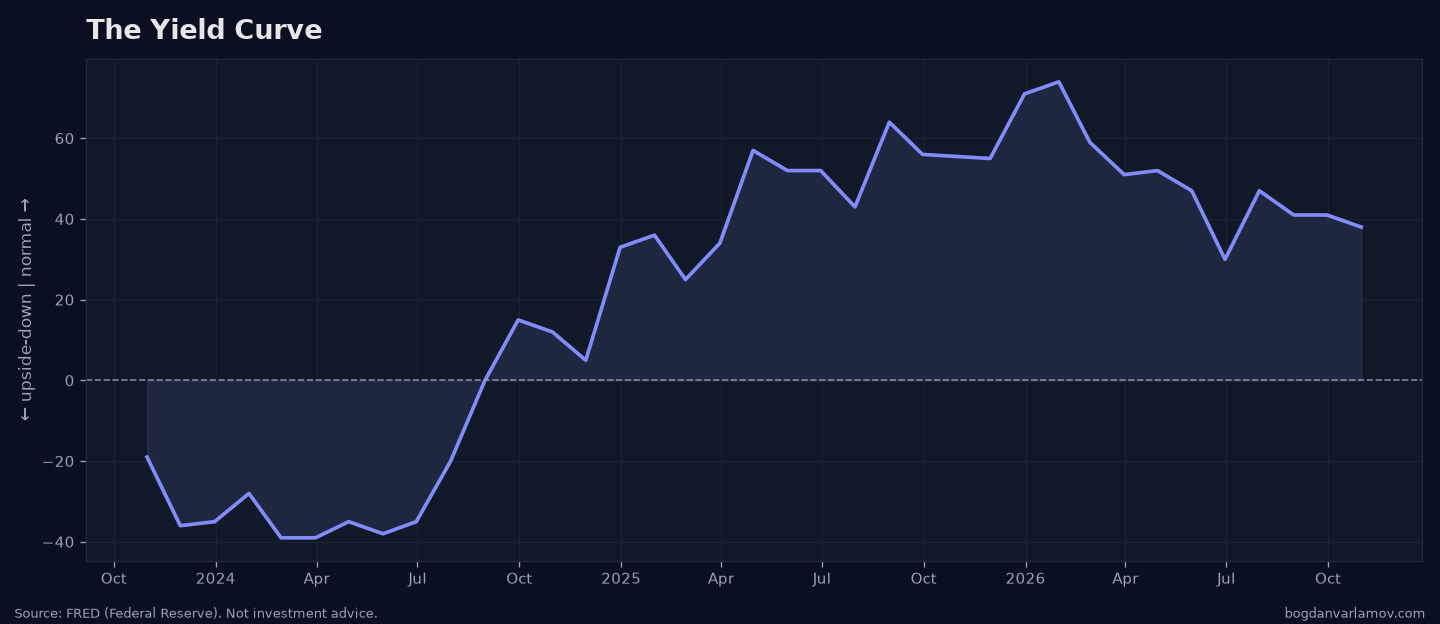
The yield curve (10-year minus 2-year).
The 30-year mortgage rate, where higher rates reach households.
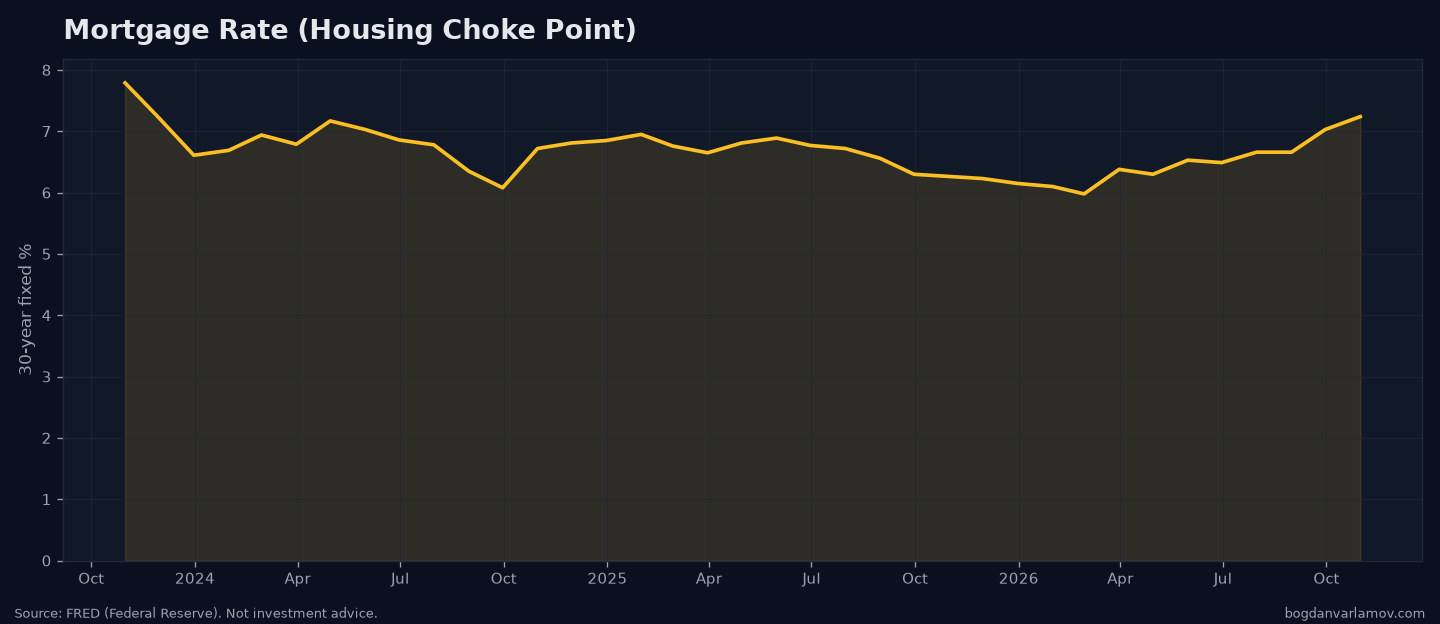
The Fed's upper target is 4.00%. The latest daily yields (Nov 4) are 4.58% for the 2-year and 4.90% for the 10-year, down from 4.61% and 4.98% on Oct 29. The 10-year fell more, so the 10y–2y gap narrowed from about +37bp to about +32bp. The gap is still positive. The 30-year mortgage rate is 7.18% (Nov 5).
The labor market
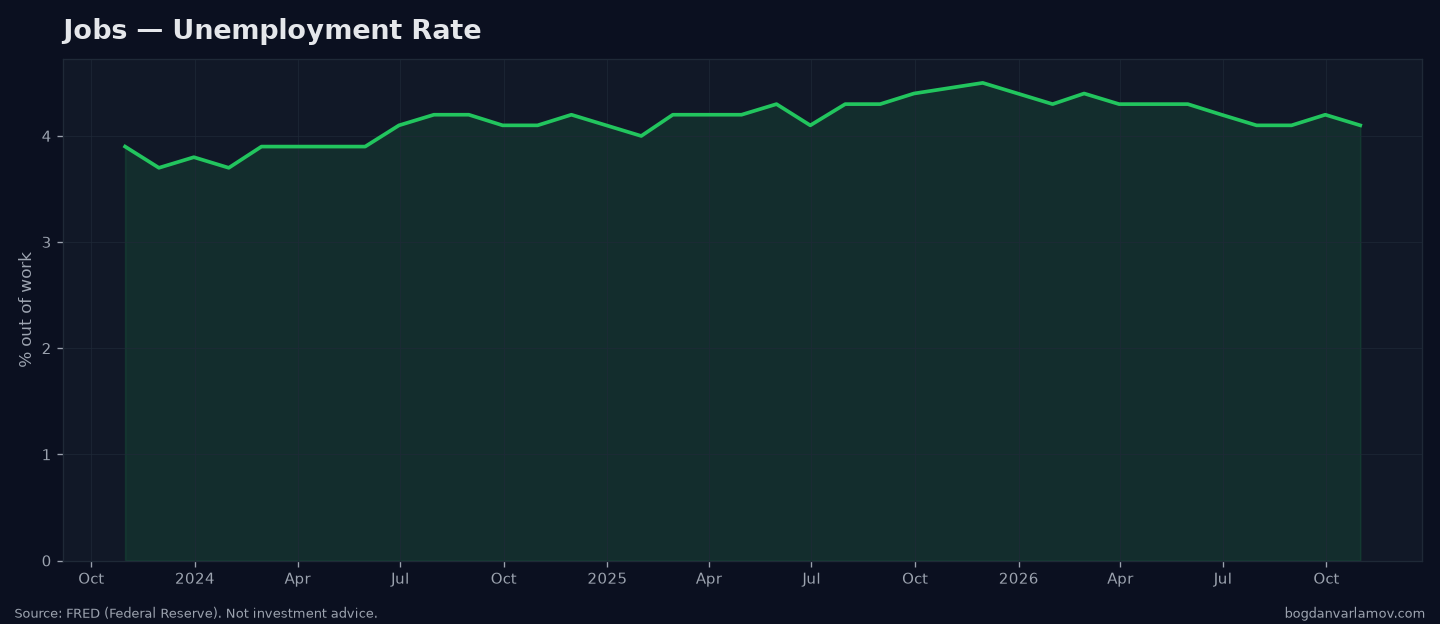
Unemployment.
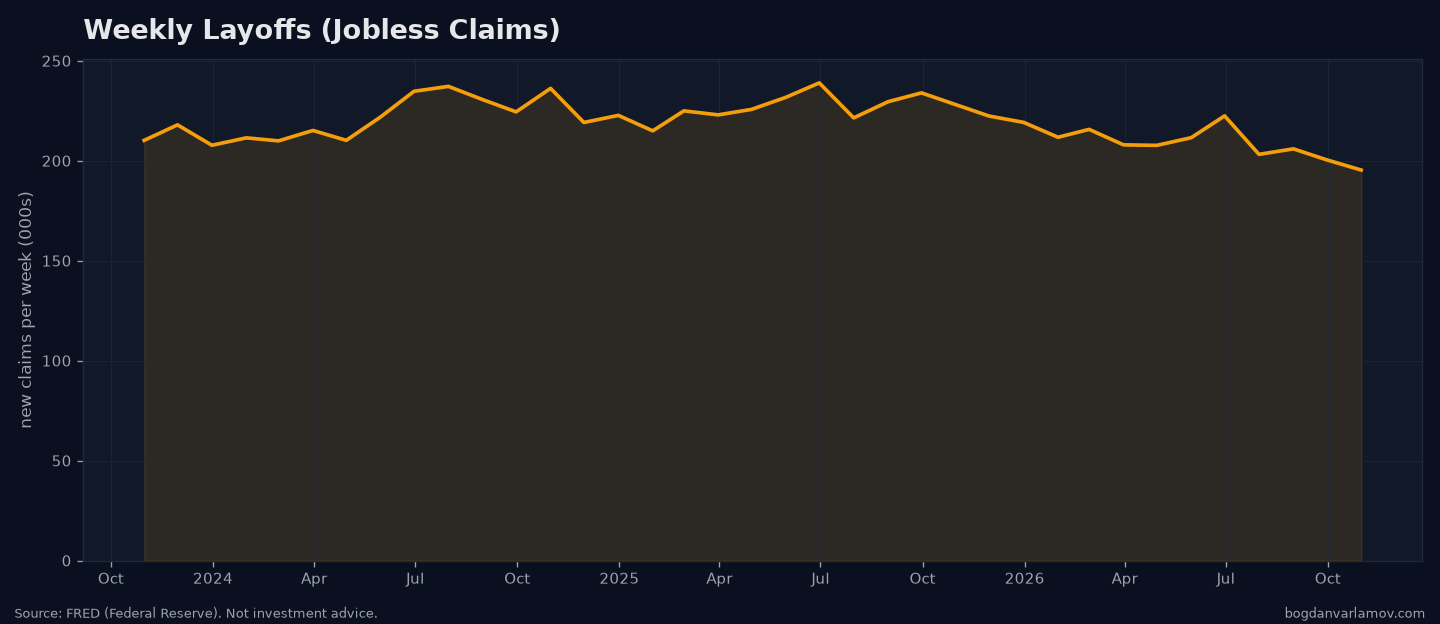
Weekly jobless claims, a fast signal from the job market.
The October jobs report was the main news. Payrolls grew +165k, and unemployment fell to 4.1% from 4.2% in September (4.4% a year ago). The revisions raised September payrolls from +29k to +60k, and August from +133k to +186k. Participation rose to 61.9% from 61.8%, so people who left the labor force do not explain the lower unemployment rate. The Sahm rule does not trigger: the 3-month unemployment average (~4.13%) is at its 12-month low.
Forward-looking stress gauges
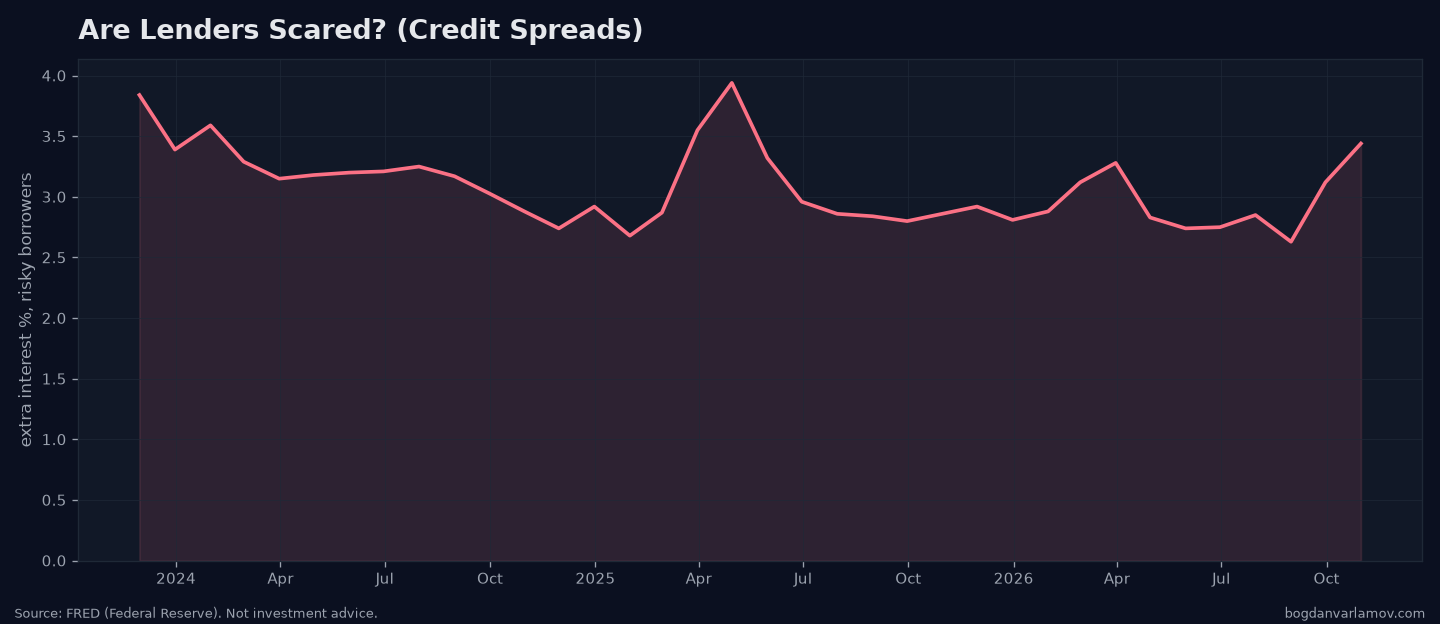
High-yield credit spreads, which show how much risk lenders see.
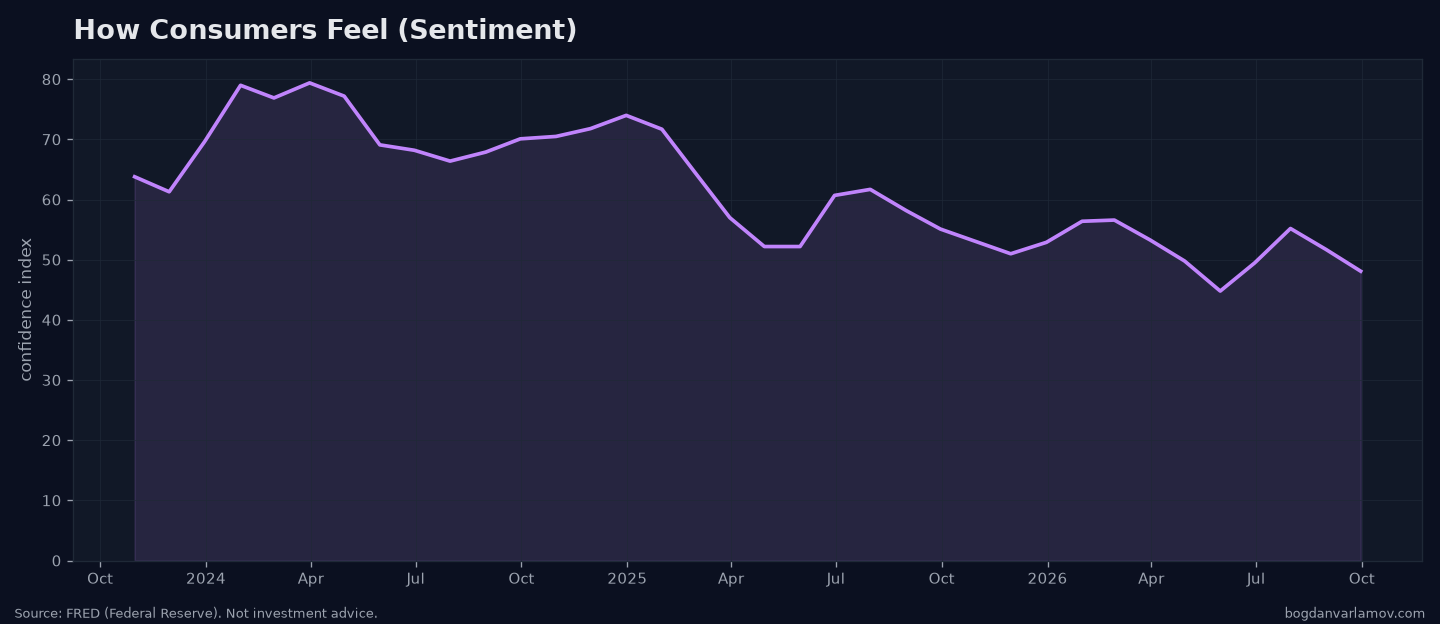
Consumer sentiment, which leads spending.
GDP growth, the last of these figures to arrive.
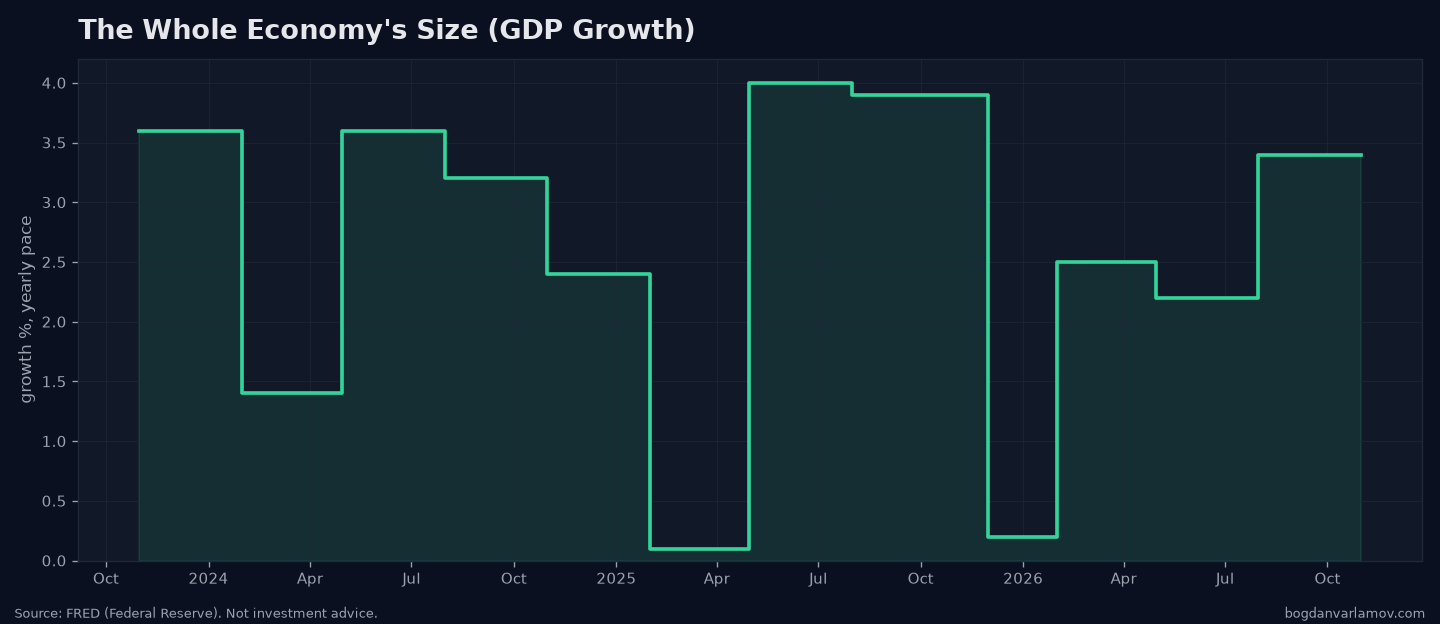
Claims and credit are mixed. Weekly jobless claims fell to 189k (week of Oct 31) from 194k, far below the ~260k tripwire. High-yield spreads widened to 3.48% (Nov 5) from ~3.3% last week and 2.85% three months ago. High-yield spreads are the one gauge that moved the wrong way, and they are still below the ~4–5% stress zone. Q3 GDP was 3.4%. Rates and energy put the pressure on households (real disposable income growth 0.95%, savings rate 3.8%). Layoffs are low.
The next twelve months
The model puts rough odds on each path below. The odds are the model's judgment.
Base case (~55%): Muddle-through / soft landing. The base case holds at ~55%. Growth stays positive (Q3 GDP 3.4%) and the job market stays strong: +165k in October, unemployment 4.1%, claims 189k. Inflation is still the main risk. October oil averaged ~$108 and the 3-month CPI rate is 4.6%, so the Fed, at 4.00%, has little room to cut. A firm jobs report gives the Fed less reason to cut.
Bear case (~25%): Consumer-led / rate-squeeze recession. The bear case fell from ~30% last week. This case needed hiring to fade further from the +29k September figure. Instead the revision raised September to +60k, October added +165k, and unemployment fell to 4.1%. The squeeze is still real: 2-year ~4.6%, 30-year mortgage 7.18%, a 3.8% savings rate and real income growth under 1%. The tripwires are claims above ~260k and a yield curve inversion, and neither is close (189k, ~+32bp). Wider spreads (3.48%) and a curve 5bp flatter stop a further drop in this case.
Bull case (~20%): Re-acceleration. The bull case rose from ~15% last week. Stronger hiring, higher participation and oil under $100 all support this case. The case still needs oil below ~$90 and a move in inflation back toward 2% so the Fed can stop at 4.00% and later cut. With a 4.6% 3-month CPI rate, inflation has not started to move back toward 2%.
What to watch next
These tripwires would change the call:
- Yield curve inversion (10y–2y below 0): ~+32bp on the latest daily reading, down from ~+37bp last week. The curve is not close to inversion.
- Weekly jobless claims that rise above ~260k and stay there: latest 189k, down from 194k. Claims are not close to the tripwire.
- Sahm rule (3-month unemployment average 0.5pp above its 12-month low): ~4.13%, at its low. The average shows no gap above its low.
- Oil above ~$95: latest $99.64, down from ~$103. October CPI (due mid-November) will show how much of October's ~$108 average reached prices.
- High-yield spreads above ~4–5%: 3.48%, up from ~3.3% last week and 2.85% three months ago. High-yield spreads are the gauge to watch most closely right now.